Investment properties welcome
Put your property's equity to work. Explore financing for your primary home, a second home or an investment property.3
Checking your rate will not affect your credit score4
Featured in

 REAL SIMPLE
Put your property's equity to work. Explore financing for your primary home, a second home or an investment property.3
Take the first step with confidence. Preview your personalized rate options with an initial check that leaves your credit score unchanged.4
Move your plans forward from wherever you are. Start your application online in minutes, with SABIZ by your side.2
Think bigger about what's next. Explore financing from $15,000 to $750,000 for home improvements, debt consolidation or your next project.3
Find an option that fits your goals. Explore fixed and variable rates with guidance to help you choose.1
Keep the process simple: your origination fee comes directly out of your initial funding, with the details clearly outlined in your offer.5
Get to closing with a team by your side. Enjoy the convenience of online notarization where available and guidance along the way.2
Keep more flexibility as your plans evolve. Maintain your line without an annual fee and pay it off early without a prepayment penalty.5
A HELOC is a revolving line secured by your home. You draw what you need (up to your credit limit), repay, and can draw again — similar to a credit card, but typically at lower rates because it’s secured.1
No in-person appraisal needed for loans under $400K. Prequalification won’t affect your credit score4.
You’ll instantly see your HELOC options for eligible properties held solely, jointly, in a revocable trust, or by an LLC.
Take advantage of the option to take additional draws as needed.
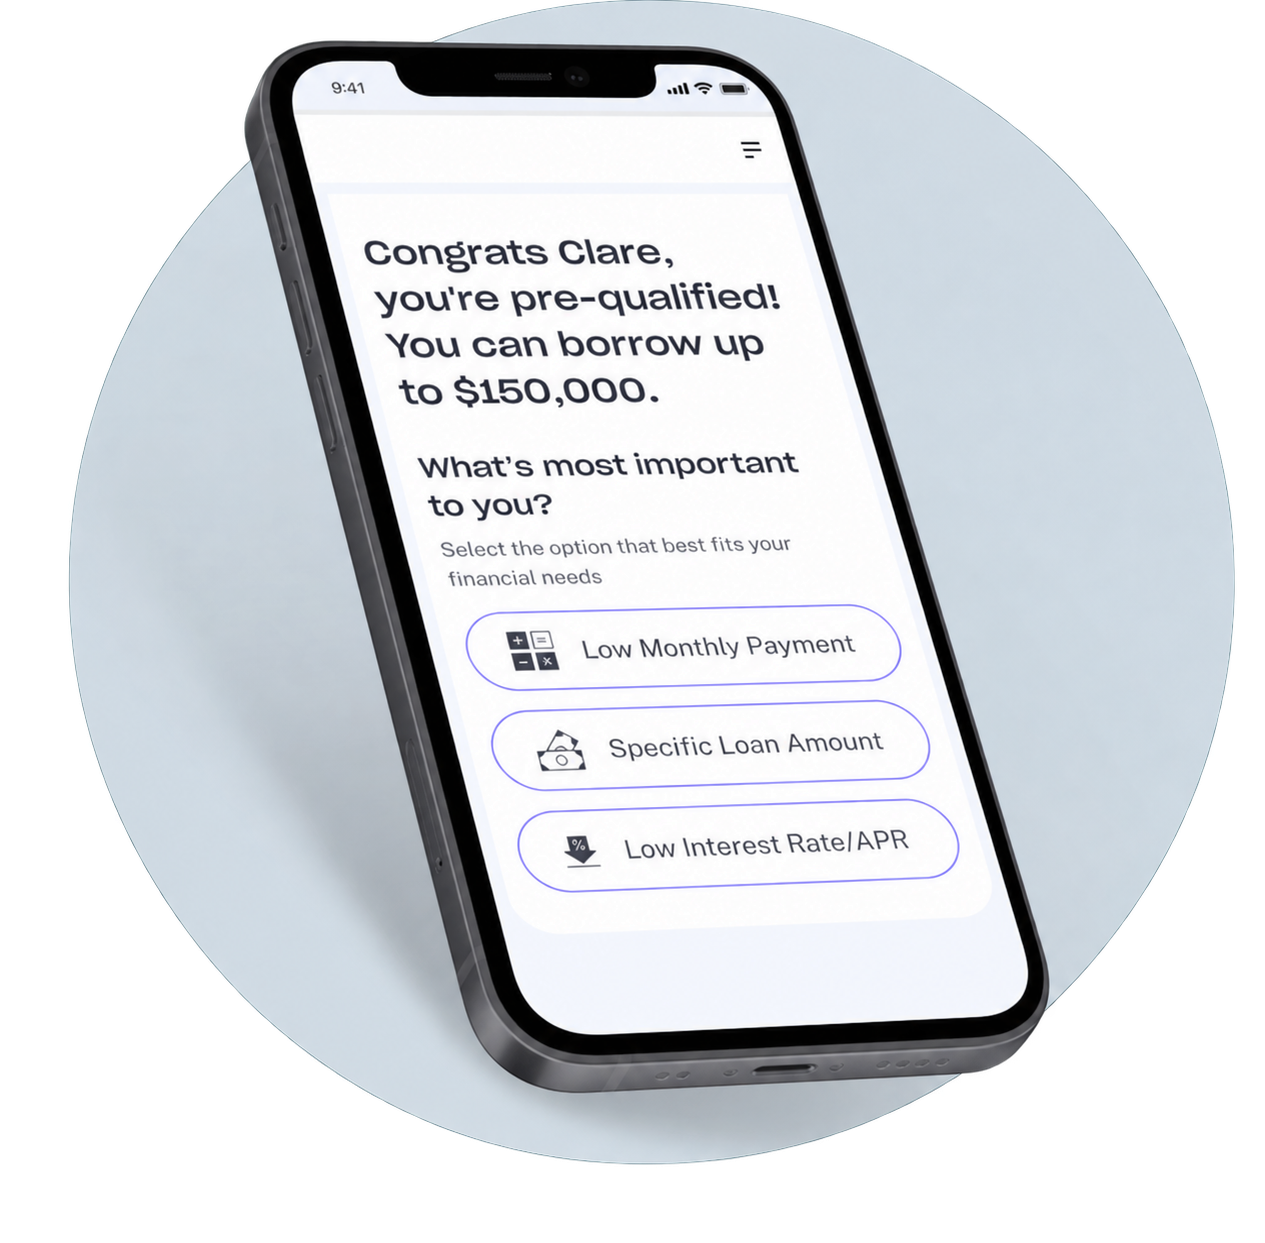
Explore your options and see why our straightforward online application, quick funding, and competitive rates make us the smart choice for your financial needs.
| Features | Our HELOC | Traditional Bank HELOC | Average Personal Loan |
|---|---|---|---|
| Application | 100% online, see your rate instantly | Varies by lender, may require in-person processes | Varies by lender |
| Prepayment penalty | Never | Possible, varies by lender | Possible |
| Tax deductible | For home improvement (be sure to consult a tax professional)7 | For home improvement (be sure to consult a tax professional) | Not tax deductible for personal use |
| Funding speed | Funding in as few as 5 days on loans under $400k2 | Could be weeks | Varies, generally quick |
| Average APR | Competitive rates5 | Variable rates, potentially higher | Typically higher than HELOCs |
For what you have in mind
A HELOC can be used for many different purposes such as:
Finance your next project.
Tap equity to simplify debt into one easy payment.
Pay for college tuition at a lower rate.
Finance your business ventures.
Major purchases, and more.
Put your home equity toward a down payment.
Adjust the chart below to create the custom amount that relates to you.
The amount you can borrow with a HELOC will vary based on certain factors such as the appraised value of your home and what percentage of that value the lender will allow you to borrow.
Our HELOC loan amounts range from a minimum of $15,000 to a maximum of $750,000.3
Checking your rate today won’t impact your credit!
In this scenario, you could qualify to borrow up to
These values do not leave equity available under the 80% assumption. Adjust the home value or remaining mortgage.
Check Out Your Rate*Based on borrowing 80% of your current home value
Let's answer your questions
A home equity line of credit, or HELOC, is a revolving line of credit. Instead of receiving a one-time loan amount as you do with a traditional loan, a HELOC gives you a borrowing limit (or credit limit). As you repay the balance, you can withdraw money from the credit line as you would with a credit card when you need it. A HELOC is secured by your home as collateral.
Your monthly HELOC payment depends on your loan amount, interest rate, term, fees and additional draws. Review the payment shown in your offer.
A home equity loan provides a lump sum with fixed payments and interest, usually over 5 to 20 years, and is often used for major home repairs or debt consolidation. In contrast, a traditional HELOC offers a flexible credit line for ongoing expenses, allowing you to borrow as needed over a set period. Our HELOC gives you the full amount upfront with fixed or variable interest rate options, but like a traditional HELOC, you can borrow again once part of the principal is repaid.1
To qualify for a HELOC, you must have sufficient equity in your home, meaning the amount you owe must be less than the home's current value. Lenders typically allow borrowing up to 85% of the home's value minus what you owe. Besides equity, lenders consider factors like credit score, credit history, employment, income, debt payments, and debt-to-income ratio to determine approval, credit line amount, and interest rate. The qualification process is similar to applying for a mortgage, so it's important to research and ensure you meet specific lender requirements before applying.
Yes. Our HELOC accepts properties held in LLCs as eligible collateral, as long as all standard underwriting requirements are met.
You may be able to deduct interest paid on a home equity product if the loan is used for home improvement. You should consult a tax advisor regarding the deductibility of interest and charges.
There are lenders that offer both variable rate and fixed interest rate home equity lines of credit. Our HELOC offers both fixed and variable options so you can choose the option that works best for you. A fixed-interest rate HELOC can provide payment predictability and peace of mind for borrowers. A variable-interest rate can change over time and follows the market. Some months your payment could be higher, and some months it could be lower.
Most applicants can complete the application in 5 minutes and you'll receive the results of your prequalification request immediately. However, final approval is subject to verification of income and employment, as well as the condition of the property.2
Apply online in minutes, with funding in as few as 5 days. Enjoy competitive rates and get the funds you need, fast.2
Find my HELOC rateSubject to credit approval and program requirements. Your loan documents govern.
Lender: PRMG, NMLS #75243. Ariel Saavedra, MLO, NMLS #2679529. Check the lender's license ↗. Equal Housing Opportunity.
Applications for properties in New York are not accepted through this program. PRMG licenses ↗ · PRMG privacy policy ↗ · PRMG terms of use ↗.